POSTED BY:
COMMENTS:
0
POST DATE:
Sharp Collect vs FairMoney vs Carbon vs Branch vs Palmcredit — Who Will Lend to You, and Why Your Last Application Got Rejected
Your App Rejected You? Here Is the Real Reason
You downloaded the app. You filled in your details. You submitted your BVN. And then — rejection. No explanation. No second chance. Just a cold "you are not eligible at this time." Thousands of Nigerians — salary earners, NYSC corpers, civil servants, students — get rejected by loan apps every single day, not because they are irresponsible borrowers, but because they did not understand the loan app eligibility Nigeria rules before applying. Here is the truth nobody tells you: every loan app in Nigeria runs its own invisible checklist. What qualifies you for FairMoney may disqualify you on Carbon. What makes Branch approve you instantly may cause Palmcredit to ghost you completely. And Sharp Collect operates on a different scoring model entirely. This guide breaks it all down — fees, hidden conditions, bureau checks, and app-specific quirks — so the next time you open a loan app, you walk in prepared, not desperate.Why Loan App Eligibility Rules Differ Across Platforms
Loan apps in Nigeria are not commercial banks. They do not have your salary advice, your employer verification letter, or ten years of account history. Instead, they use proprietary algorithms, data-scoring models, and licensed credit bureau checks to decide who is a safe borrower. Because each company built its own risk model, each one weighs variables differently. One app might care deeply about how consistently you receive bank alerts on your phone. Another might prioritise your CRC Credit Bureau score above everything else. A third might almost entirely rely on smartphone metadata. This is why the same person can collect ₦80,000 from FairMoney and receive a flat rejection from Carbon on the same afternoon. It is not personal. It is algorithmic. And once you understand how each system is wired, loan app eligibility in Nigeria becomes a game you can actually win.The 5 Things Every Nigerian Loan App Checks Before Saying Yes
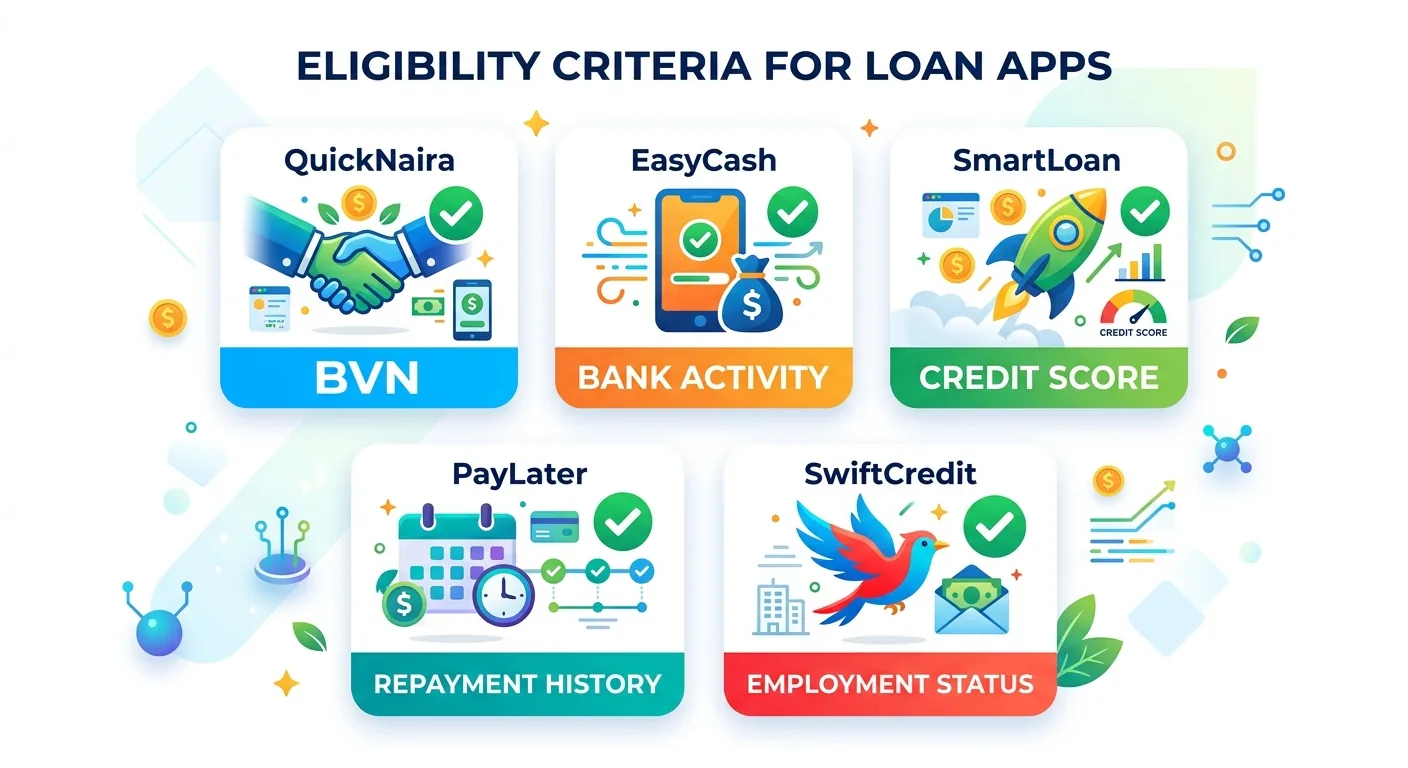
Before we go app by app, here are the five universal checkboxes that cut across all platforms. Understanding these is the foundation of improving your loan app eligibility in Nigeria.① BVN — Your Financial Identity Card
Non-negotiable. Every serious loan app requires your BVN. It links your legal identity to your banking activity across every account you have ever opened in Nigeria. No BVN, no loan — full stop. Dial *565*0# on any network to confirm yours is active and accurate.② Phone Number History
Your phone number is more powerful than most people realise. Apps check how long you have used the number, whether it matches your BVN record, and sometimes how active your data usage is. A brand-new SIM card is a yellow flag that can trigger automatic rejection.③ Bank Account Activity
Most apps connect to your bank via statement analysis or open banking APIs. They look at inflow frequency, average monthly balance, and repayment behaviour patterns. A dormant or erratic account is a hard red flag — even if your balance is temporarily high.④ Credit Bureau Record
CRC Credit Bureau and FirstCentral Credit Bureau hold your full Nigerian loan history. If you have defaulted on any loan app previously — even one you forgot about from 2021 — it will show up and damage your loan app eligibility across the board.⑤ Smartphone Metadata — For Select Apps
Some apps, with your explicit permission, analyse your phone — SMS bank alerts, app usage patterns, even your contact list size — to build a credit profile from scratch. This is how they extend credit to people with no formal employment record.App-by-App Loan App Eligibility Breakdown
FairMoney — The People's App
Who it approves: Salary earners, NYSC members, civil servants, and low-to-mid income workers with active bank accounts and consistent transaction history. Core requirements: - Nigerian citizen with a valid, active BVN - Active bank account with any major institution — GTBank, Access, Zenith, OPay, Kuda, Wema, etc. - Functional Android smartphone (iOS support remains limited as of 2025) - No active loan default on the FairMoney platform Loan range: ₦1,500 – ₦3,000,000 Eligibility edge: FairMoney is the most accessible entry point for first-time borrowers. If your bank account shows at least three to six months of consistent inflows, your approval odds are strong. They also treat NYSC monthly allowances as legitimate qualifying income — a policy that most other apps do not match. Who struggles here: Anyone with zero bank transaction history or multiple unresolved defaults with other lenders on the credit bureaus.Carbon (Formerly Paylater) — The Premium Player
Who it approves: Formally employed salary earners, professionals, and borrowers with a clean, trackable credit bureau history. Core requirements: - Valid BVN - Bank account with verifiable, recurring salary or income inflows - Completed profile including employment status and employer name - Good CRC and FirstCentral credit scores — Carbon takes bureau checks seriously Loan range: ₦1,500 – ₦1,000,000 Eligibility edge: Carbon rewards loyalty aggressively. Borrow and repay on schedule three times in a row and your limit escalates fast. Being an active Carbon account holder — with savings and bill payments on the platform — also lifts your loan app eligibility score internally. Who struggles here: First-timers with no credit footprint and NYSC corpers without supplementary formal income. Carbon is built for people who already exist meaningfully in Nigeria's formal financial system.Branch — The Data-Driven Qualifier
Who it approves: Anyone with an active Android smartphone, consistent bank alert patterns, and a clean credit history — formal employment is not required. Core requirements: - Valid BVN - Android smartphone — Branch does not function properly on iOS - Active bank account with regular transaction history - Permission to access phone data — SMS alerts, contacts, app behaviour Loan range: ₦500 – ₦500,000 Eligibility edge: Branch is the most unique model of the five. It builds your credit profile partly from your phone — your SMS bank alerts, how frequently you receive and send money, even how many legitimate contacts you have saved. This makes Branch genuinely accessible to informal workers, as long as your phone reflects real financial activity. Who struggles here: iPhone users (the platform is Android-first by design), people with SIM cards under three months old, and anyone who refuses to grant data access permissions.Palmcredit — The Flexible Entry Point
Who it approves: Low-to-middle income earners, first-time borrowers, people needing small emergency loans without heavy documentation requirements. Core requirements: - Valid BVN - Valid Nigerian phone number registered to your BVN - Active bank account with some transaction history - Basic personal and next-of-kin information Loan range: ₦2,000 – ₦300,000 Eligibility edge: Palmcredit carries the lowest barrier to entry across all five apps. They are more forgiving with first-time and thin-file borrowers. If you have a working BVN and a reasonably active account, a starter loan is often achievable. This makes Palmcredit an important first rung on the credit-building ladder for Nigerians with limited loan app eligibility history. Who struggles here: Repeat defaulters. Palmcredit may feel relaxed at the front door, but they report every default to credit bureaus promptly — and those records will chase you across every other app on this list.Sharp Collect — The Structured Challenger
Who it approves: Regular salary earners, workers in organised employment, and Nigerians looking for a transparent personal loan process with clear terms upfront. Core requirements: - Valid BVN - Active Nigerian bank account - Valid NIN (National Identification Number) preferred - Employment or verifiable income — may request bank statement analysis Loan range: Typically ₦5,000 – ₦500,000 depending on profile and credit history Eligibility edge: Sharp Collect is built for Nigerians who want clarity before they borrow. The platform positions itself on fee transparency and structured eligibility — no algorithmic smoke and mirrors. If you are a salary earner or civil servant with a clean BVN record, Sharp Collect gives you a straightforward path to credit without the guesswork. Who struggles here: Completely informal workers with no verifiable income paper trail and borrowers carrying multiple unresolved defaults from previous lenders.Special Section: Can NYSC Corpers Get Loans From These Apps?
This is one of the most searched questions about loan app eligibility Nigeria — and the answer is yes, but not from all apps equally. NYSC corpers receive a monthly federal government allowance currently pegged at ₦33,000, often supplemented by state bonuses and Place of Primary Assignment (PPA) top-ups. This is real, recurring, documentable income — and certain apps are smart enough to recognise it.Best Options for NYSC Corpers
- FairMoney — The most corper-friendly app on this list. If your NYSC allowance hits your bank account monthly without fail, FairMoney will treat it as qualifying income. Thousands of corpers across Nigeria have accessed credit through this route.
- Palmcredit — Accessible for corpers with active bank accounts and a clean BVN record.
- Branch — Works effectively if your phone and bank account data show consistent financial activity, regardless of employment type.
Harder for NYSC Corpers
- Carbon — Prefers more established employment history with a traceable salary structure.
- Sharp Collect — The structured employment focus can disadvantage corpers who lack supplementary formal income.
Civil Servants and Salary Earners — Which Apps Favour You?
If you receive a regular salary — whether from a federal ministry, a state government, or a private employer — you hold a genuine advantage in the loan app eligibility Nigeria game. Loan apps love predictable, recurring income above almost everything else.Top Picks for Salary Earners and Civil Servants
- Carbon — Built almost perfectly for formal employees. A consistent monthly salary alert pattern is your golden ticket to higher limits and lower interest rates.
- FairMoney — Strong option with one of the highest loan ceilings at ₦3,000,000 for proven salary earners.
- Sharp Collect — Structured specifically for regular income earners; positions itself as the transparent choice for workers who want to understand exactly what they are signing up for before they borrow.
Students and Low-Income Workers — Who Will Lend to You?
Students and low-income informal workers face the steepest climb in loan app eligibility Nigeria — but it is not an impossible one.Realistic Options for Students and Low-Income Workers
- Palmcredit — Lowest barrier to entry for starter amounts; ideal for building a credit footprint from zero.
- Branch — The phone-data model means formal employment is not required. If your phone and bank show real financial activity, Branch can work for you.
- FairMoney — Offers small starter loans even to thin-file borrowers, giving you an entry point into the formal credit system.
The BVN Factor: Why Your BVN Is Your Loan Passport
Your BVN connects your legal identity to every bank account you have ever opened in Nigeria — your name, date of birth, registered phone number, and the full list of financial institutions you are linked to. When a loan app collects your BVN, it gains a window into all of that. What this means in practical terms:- Any loan default reported to CRC or FirstCentral under your BVN will appear — regardless of how old it is or which app it originated from.
- If your BVN name does not match the name on your ID or bank account, you will be flagged for inconsistency and your loan app eligibility will be suspended pending verification.
- Using another person's BVN is financial fraud under CBN regulations and the Cybercrime Act — it is a criminal offence with real legal consequences.
How to Improve Your Loan App Eligibility Before Applying
Before you tap that "Apply Now" button, take these steps to maximise your loan app eligibility Nigeria score: ✅ Use the account where your income actually lands — salary, NYSC allowance, regular client transfers. Not a dormant backup account. ✅ Maintain a consistent transaction pattern for at least three months — small regular inflows outperform one large random deposit in every algorithm. ✅ Clear any outstanding defaults before applying, even on platforms you have moved on from. Credit bureaus share data across all registered lenders in Nigeria. ✅ Keep your profile details consistent — same full name, same phone number, same BVN-linked information across every app you use. ✅ Do not apply to five apps simultaneously. Multiple credit inquiries within a short window signal financial desperation to the algorithm and actively reduce your loan app eligibility score. ✅ Start with one app, repay perfectly, then grow. This is the fastest legitimate path to higher credit limits and stronger loan app eligibility across all platforms.Red Flags That Get Your Loan Application Rejected
These are the silent killers of loan app eligibility in Nigeria: ❌ Any unresolved default — it follows your BVN across every lender that checks CRC or FirstCentral. ❌ A SIM card under three months old or one that does not match your BVN registration. ❌ Linking an account with zero transaction history or wildly inconsistent deposit patterns. ❌ Inconsistent personal information — different spellings of your name across your BVN, ID, and app profile. ❌ Applying to multiple apps on the same day — algorithms interpret simultaneous applications as a sign that you have been rejected elsewhere and flag your profile accordingly. ❌ A consistent overdraft pattern or negative balance on the account you link — it signals that you spend more than you earn and destroys your loan app eligibility score instantly.Final Verdict — Which App Should You Try First Based on Your Situation?
| Your Situation | Best First App |
|---|---|
| Salaried private sector employee | Carbon or FairMoney |
| Federal or state civil servant | Carbon or Sharp Collect |
| NYSC corper | FairMoney or Palmcredit |
| Student with active bank account | Branch or Palmcredit |
| First-time borrower, no credit history | Palmcredit or FairMoney |
| Rebuilding credit after a past default | FairMoney (small amount first) |
| Salary earner wanting fee transparency | Sharp Collect |
