POSTED BY:

COMMENTS:

1

POST DATE:


Understanding loan app borrowing limits Nigeria is the difference between choosing the right platform and wasting your time filling forms that lead nowhere. That is exactly what we are breaking down today. No fluff. No vague promises. Just the real numbers, the real requirements, and an honest take on which app is worth your time depending on how much you actually need.  
Why Loan Apps Start You Small — And It Is Not Personal

Before we enter the numbers, let us understand the game. Loan apps in Nigeria operate without the kind of collateral traditional banks demand. They cannot collect your land document or hold your car key. So instead of physical security, they use data as collateral. Your BVN, your bank transaction history, your repayment behaviour, your phone data (for some apps), your salary pattern — all of this becomes your financial fingerprint. The app feeds this into an algorithm that decides: "How much can we safely lend this person without losing our money?" When you are new, that fingerprint is incomplete. The algorithm does not know you yet. So it offers you a small amount — not to insult you, but to test your repayment character. Pay that small loan on time, and your limit climbs. Default or pay late, and you may stay stuck at the bottom forever. This is why loan app borrowing limits Nigeria are not fixed numbers — they are dynamic ceilings that change based on your behaviour. The CBN's regulatory framework for digital lenders, which tightened significantly between 2022 and 2024, also requires licensed apps to perform credit bureau checks before disbursing. This means your CRC or FirstCentral score is actively being pulled every time you apply. Now, let us look at what each app actually offers. loan app borrowing limits Nigeria

FairMoney Borrowing Limit Breakdown — Nigeria's Highest Ceiling App

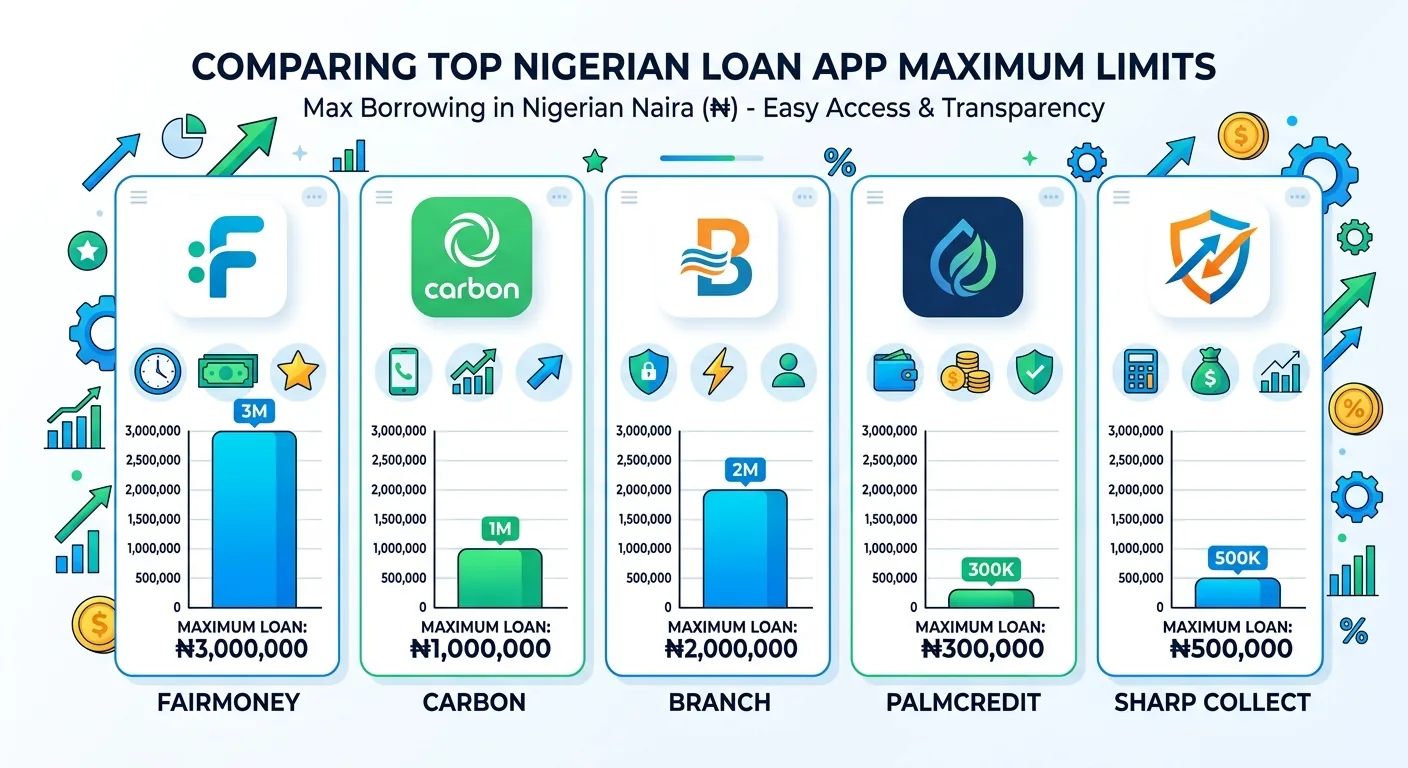
FairMoney is one of the most widely used loan apps in Nigeria, and for good reason. It holds a full microfinance banking licence from the CBN, which means it can offer higher amounts than many competitors operating as simple lenders. Minimum starting loan: ₦1,500 – ₦10,000 (for new users with limited data) Realistic first-loan range: ₦5,000 – ₦30,000 Maximum reported limit: Up to ₦3,000,000 for well-established users with strong repayment history and verifiable income

What Affects Your FairMoney Borrowing Limit

  • Bank statement data, especially consistent salary credits from employers
  • Speed and consistency of previous repayments within the platform
  • Whether you have linked a salary account or actively used the FairMoney bank account
  • Your CRC or FirstCentral credit bureau score
  • Employment verification and monthly income declared in your profile
FairMoney is one of the few apps where salary earners who receive alerts directly into their linked bank account unlock higher limits faster. If your salary is your strongest financial proof, FairMoney rewards that clearly and progressively. Loan tenure: 1 month to 18 months depending on amount and user profile Interest rate: Approximately 10%–30% per annum, though effective monthly cost varies based on risk assessment and tenure selected For salary earners, civil servants, and SME owners with documented income, no other app on this list comes close to FairMoney's ₦3 million potential when considering loan app borrowing limits Nigeria.

Carbon Borrowing Limit Breakdown — Best for Loyal Digital Banking Users

Carbon, formerly known as Paylater, is one of Nigeria's original loan apps and has since evolved into a full digital bank licensed by the CBN. It is known for being conservative at the entry level but increasingly generous to loyal users who engage with other Carbon products beyond just borrowing. Minimum starting loan: ₦1,500 – ₦5,000 Realistic first-loan range: ₦5,000 – ₦20,000 Maximum reported limit: Up to ₦1,000,000 for users with clean repayment history and active Carbon account usage

What Affects Your Carbon Borrowing Limit

  • Whether you save or transact regularly using the Carbon app
  • Your credit bureau record across CRC and FirstCentral
  • Repayment history specifically within Carbon's system
  • Employment verification or bank statement uploads
  • Frequency of salary credits on your linked bank account
Carbon rewards users who treat it as more than just an emergency loan app. If you use Carbon Pay, maintain savings on the platform, or receive regular income alerts, your borrowing ceiling climbs more noticeably than users who only open the app when they need cash. Loan tenure: 1 to 12 months Interest rate: From 5% monthly, but varies significantly based on your risk profile and how long you have been on the platform For understanding how loan app borrowing limits Nigeria scale with platform loyalty, Carbon is one of the clearest examples — your limit is directly tied to how embedded you are in their ecosystem.

Branch Borrowing Limit Breakdown — Best for Nigerians Without Formal Payslips

Branch is a US-backed fintech that operates across Kenya, Tanzania, India, and Nigeria. In Nigeria, it uses a heavily data-driven approach — analysing your phone's SMS history, financial transaction patterns, and spending behaviour before calculating your limit. Minimum starting loan: ₦2,000 – ₦5,000 Realistic first-loan range: ₦5,000 – ₦15,000 Maximum reported limit: Up to ₦500,000 for users with consistent, multi-year repayment history

What Affects Your Branch Borrowing Limit

  • Your phone's SMS data, including bank alerts, bill payments, and airtime purchases
  • Repayment speed — paying early or on the exact due date carries measurable algorithmic weight
  • Frequency of completed borrowing and repayment cycles
  • Social and financial footprint detectable from device data
Branch is particularly accessible for Nigerians without formal employment because it leans on phone data more than payslips or bank statements. An Aba trader with strong phone-based transaction history may qualify for a decent Branch limit while being rejected by apps that require employment letters. However, this flexibility also means your ceiling may be lower compared to income-verified platforms. The ₦500,000 maximum is achievable but requires sustained loyalty over many loan cycles — typically 12 or more successful repayments. Loan tenure: 4 weeks to 12 months Interest rate: Approximately 15%–34% annually, which translates to roughly 1.3%–2.8% monthly depending on the tenor you select Branch does not publish its exact rates upfront, which is a transparency gap worth noting. Always check the final repayment amount shown before accepting any loan offer. According to the CBN's 2023 framework on digital lending transparency, all licensed digital lenders are required to disclose the full cost of credit before disbursement.

Palmcredit Borrowing Limit Breakdown — Best for Regular Small-Loan Borrowers

Palmcredit is among the most accessible apps for first-time borrowers in Nigeria, with loan decisions frequently delivered within minutes of application. It uses a clear tiered system that makes it easier to understand how your limit grows — which is a genuine advantage when navigating loan app borrowing limits Nigeria. Minimum starting loan: ₦2,000 – ₦8,000 Realistic first-loan range: ₦5,000 – ₦20,000 Maximum reported limit: Up to ₦300,000 for high-tier loyal users

What Affects Your Palmcredit Borrowing Limit

  • Repayment history specifically within Palmcredit — external history matters less here
  • BVN-linked financial data and phone number verification
  • Credit bureau checks via CRC
  • Number of completed loan cycles within the platform
Palmcredit works in explicit tiers — Bronze, Silver, and Gold — and each clean repayment cycle moves you upward. Each tier unlocks a higher ceiling and sometimes a slightly lower interest rate. For salary earners or civil servants who need ₦20,000–₦100,000 on a rolling basis, Palmcredit serves that need comfortably after three or four clean cycles. But if your target is ₦500,000 or above, this is not your best platform. Loan tenure: 91 days to 180 days — shorter than most competitors on this list Interest rate: Approximately 4%–24% monthly depending on tier and amount — note that the lower tier rates can make the effective annual cost very high

Sharp Collect Borrowing Limit Breakdown — Best for Emergency Fast Cash Under ₦50K

Sharp Collect is a fast-growing Nigerian loan platform designed with speed and accessibility at its core. It targets everyday Nigerians who need emergency cash without the complex documentation that slows down traditional lenders. Minimum starting loan: ₦3,000 – ₦10,000 Realistic first-loan range: ₦5,000 – ₦30,000 Maximum reported limit: Up to ₦200,000 for returning users in good standing

What Affects Your Sharp Collect Borrowing Limit

  • BVN verification and phone number history
  • Repayment behaviour from previous loans on the platform
  • App engagement and account activity between loan cycles
  • Credit bureau data where applicable
Sharp Collect is not the platform to use if your goal is a six-figure loan from day one. Its strength is speed and low barrier to entry — approval with minimal documentation, fast disbursement, and a straightforward user experience. For emergency cash needs under ₦50,000, it holds its own strongly against the bigger names. For anything above ₦200,000, you will need to build history here first and supplement with a higher-ceiling platform. Understanding loan app borrowing limits Nigeria across platforms like Sharp Collect matters most when you are matching the right tool to the right need. Loan tenure: 7 days to 90 days — best suited for short-term emergencies Interest rate: Varies by amount and tenure — typically higher on very short-term loans, which is standard across all platforms at this bracket

Side-by-Side Comparison Table — Loan App Borrowing Limits Nigeria 2025

App Starting Loan Realistic 1st Loan Maximum Limit Interest Rate Best For
FairMoney ₦1,500 ₦5K–₦30K ₦3,000,000 ~10%–30% p.a. Salary earners needing high limits
Carbon ₦1,500 ₦5K–₦20K ₦1,000,000 From 5% p.m. Loyal digital banking users
Branch ₦2,000 ₦5K–₦15K ₦500,000 ~1.3%–2.8% p.m. Those without formal payslips
Palmcredit ₦2,000 ₦5K–₦20K ₦300,000 4%–24% p.m. Regular small-loan borrowers
Sharp Collect ₦3,000 ₦5K–₦30K ₦200,000 Varies by tenure Emergency fast cash under ₦50K
loan app borrowing limits Nigeria

How to Unlock Higher Limits on Any Loan App — Step-by-Step Guide

This is where most borrowers leave money on the table. The algorithm is not your enemy — you just have to learn how to speak its language. These steps apply across all five platforms and directly influence your loan app borrowing limits Nigeria progression.

Step 1 — Start Small and Repay Early

Do not wait for the due date. Repay 2–3 days before the deadline on your first loan. This signals to the algorithm that you are a low-risk borrower. Apps like Branch and Carbon specifically track early repayment as a measurable positive signal that lifts your next offer automatically.

Step 2 — Avoid Borrowing on Multiple Apps at the Same Time

When you take active loans from four apps simultaneously, all three major credit bureaus — CRC, FirstCentral, and CreditRegistry — see this stacking behaviour. It reads as financial distress, and your limit on each platform may freeze or drop. One active loan at a time, completed cleanly, builds your profile faster than scattering applications across every app on the Play Store.

Step 3 — Use the App Beyond Just Borrowing

FairMoney, Carbon, and Palmcredit all carry savings, payments, or banking features. Users who engage with these features — even saving ₦500 per week — are flagged by the algorithm as financially stable rather than purely distress-driven borrowers. This directly and measurably influences your borrowing ceiling over time.

Step 4 — Link the Account Where Your Salary Actually Drops

For salary earners and civil servants especially, linking the specific bank account that receives your monthly salary is one of the most powerful limit-unlocking moves available. Consistent salary credits are among the strongest signals any loan app algorithm in Nigeria recognises when assessing loan app borrowing limits Nigeria eligibility. FairMoney and Carbon respond particularly well to this single action.

Step 5 — Complete at Least Three Clean Cycles Before Requesting a Limit Increase

On platforms like Palmcredit with explicit tier systems, you need completed cycles to advance. Three consecutive clean repayments will do more for your ceiling than any shortcut or workaround. Some apps also have in-app limit increase request buttons — use them only after completing multiple clean cycles, never on your first or second loan.

Step 6 — Keep Your Profile Information Current and Accurate

Employment status, monthly income estimate, and residential address — update these regularly. Outdated profile data can cap your limit artificially because it creates a mismatch between what your bank data shows and what your self-reported profile claims. Apps use profile alignment as a trust signal in their credit scoring models.

Which App Should You Pick Based on How Much You Need?

Here is the practical breakdown of loan app borrowing limits Nigeria matched to real-world needs at every cash level. If you need ₦5,000 – ₦30,000 urgently today: Sharp Collect or Palmcredit — fast approval, low documentation barrier, money in your account within minutes to hours. Sharp Collect specifically prioritises speed at this range with minimal friction. If you need ₦30,000 – ₦100,000: FairMoney or Carbon — better reliability at this range, especially after two or three clean cycles. Both have the infrastructure to process this amount smoothly for verified users without excessive delays. If you need ₦100,000 – ₦500,000: FairMoney or Carbon — you will need a documented income source, clean repayment history, and an established profile. Carbon users who actively bank on the platform tend to reach this range faster than loan-only users. If you need above ₦500,000: FairMoney only — this is the single app in this comparison realistically capable of reaching that ceiling. Their CBN microfinance banking licence allows them to operate at a scale the other apps cannot legally match for individual borrowers. If you have no formal employment or payslip: Branch — their phone-data model gives people outside formal employment a better shot at a meaningful limit. Traders, freelancers, and gig workers tend to perform better on Branch than on income-document-dependent platforms.

Comment (1)

  • Ojims September 14, 2026 Reply

    Please I need a loan

Leave a Reply

Your email address will not be published. Required fields are marked *