Why Your Salary Disappears Before the Month Ends (And What Actually Fixes It)
Every month follows the same script. Salary arrives. Rent takes a chunk. Feeding, transport, data, and one "small" emergency later — and you are back to zero by the 20th. No drama. No big spending. Just the quiet, consistent leak that leaves Nigerian salary earners with nothing to show for twelve months of work.
This is not a willpower problem. It is a structure problem. And automated savings apps Nigeria workers can download today — PiggyVest, Cowrywise, and Kuda — exist specifically to replace willpower with a system that works even when your motivation does not.
This guide covers exactly how to use them to build a real emergency fund in 2025 — even if you earn ₦50,000 a month.
Why Nigerian Salary Earners Have No Emergency Fund
Most salary earners in Nigeria — civil servants, NYSC members, hospital staff, teachers, bank clerks, call centre agents — spend their salary within the first two weeks of receiving it. Not because they are careless. Because the pressure is real and the system offers zero protection.
A 2024 survey by a Lagos-based financial inclusion research group found that over 68% of Nigerian workers earning between ₦50,000 and ₦200,000 monthly have less than one month's salary saved at any point. Many had zero savings.
Three reasons drive this:
No automatic mechanism to save before spending starts. When salary lands and ten expenses are waiting, money moves out before any deliberate decision is made.
Traditional bank savings accounts have zero friction. Zenith, GTB, Access — every one lets you withdraw in seconds. No lock. No penalty. No barrier between you and your savings.
"I will save what is left at end of month" — which is never anything. End-of-month savings is a fantasy. The automated savings apps Nigeria workers are adopting in growing numbers exist specifically to kill this habit permanently.
What Automated Savings Actually Means
Automated savings means you set one instruction and the app pulls money from your account on a schedule you choose — without you touching anything again.
No remembering. No willpower required on payday. The money moves before your hands reach it.
Think of it this way: if your landlord collected rent by direct debit, you would find a way to have that money ready every single month. Automated savings runs the exact same psychology — it makes saving feel like a bill you already owe yourself.
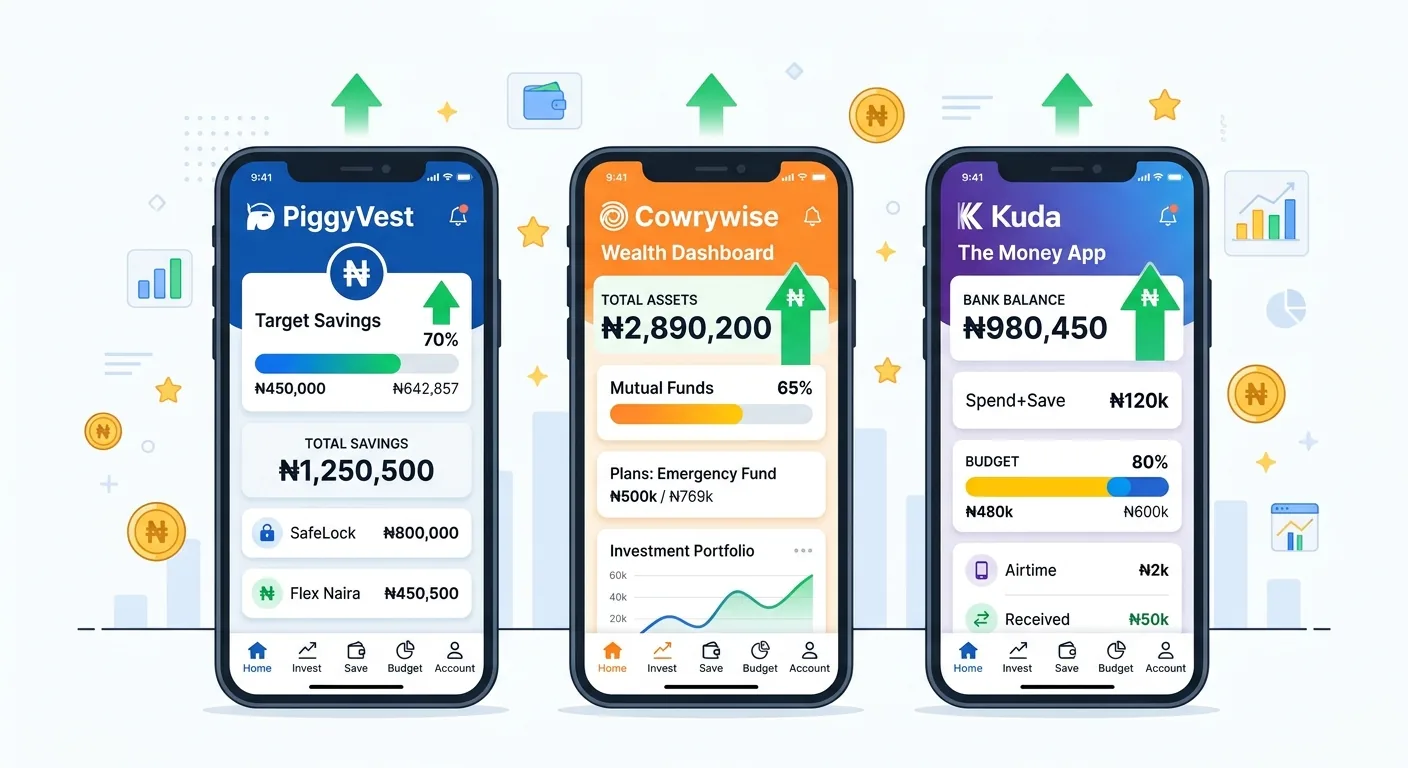
The three automated savings apps Nigeria professionals rely on most in 2025 each take a different approach. Understanding the difference determines which one actually fits your income level.
Platform Breakdown: PiggyVest, Cowrywise, and Kuda
PiggyVest — The Original Lock-Your-Money App
PiggyVest is the foundation of automated savings apps Nigeria built its savings culture on. Their core features are SafeLock and the PiggyBank automated savings function.
- Set daily, weekly, or monthly automatic deductions
- Money is locked until your chosen end date — early withdrawal costs a penalty (typically 10% of earned interest)
- Interest rate: approximately 10–13% per annum in 2025
- Minimum to start: ₦100 per day
The psychological power of PiggyVest is the lock itself. For anyone who knows their own weakness — "if I see it, I will spend it" — this is the strongest single tool among all automated savings apps Nigeria currently offers.
Cowrywise — The Goal-Based Savings Platform
Cowrywise structures savings around named financial goals. Their Circles feature also allows group savings for shared targets.
- Create named savings buckets: Emergency Fund, School Fees, House Rent — each kept separate
- Automated deductions run on your chosen schedule
- Interest rate: approximately 8–12% per annum depending on plan duration
- Minimum: ₦100
Cowrywise suits salary earners who want to see exactly where each naira is going without everything collapsing into one account that evaporates by month-end.
Kuda — The Digital Bank With Automation Built In
Kuda is a full digital bank whose Spend+Save feature and Savings Pockets make it a legitimate entry point into automated savings apps Nigeria workers are using daily.
- Spend+Save automatically saves a percentage of every debit transaction — every time you spend, a small cut goes to savings without any action from you
- Fixed automated transfers into a savings pocket are also available
- Interest rate: approximately 8–10% per annum
- No minimum balance required
Kuda's key advantage: it lives where your money already is. If your salary arrives in Kuda, the automation runs without a single extra step.
The ₦500-a-Day Strategy That Builds ₦180,000 Without You Noticing
Here is a concrete calculation for someone earning ₦80,000 to ₦150,000 monthly.
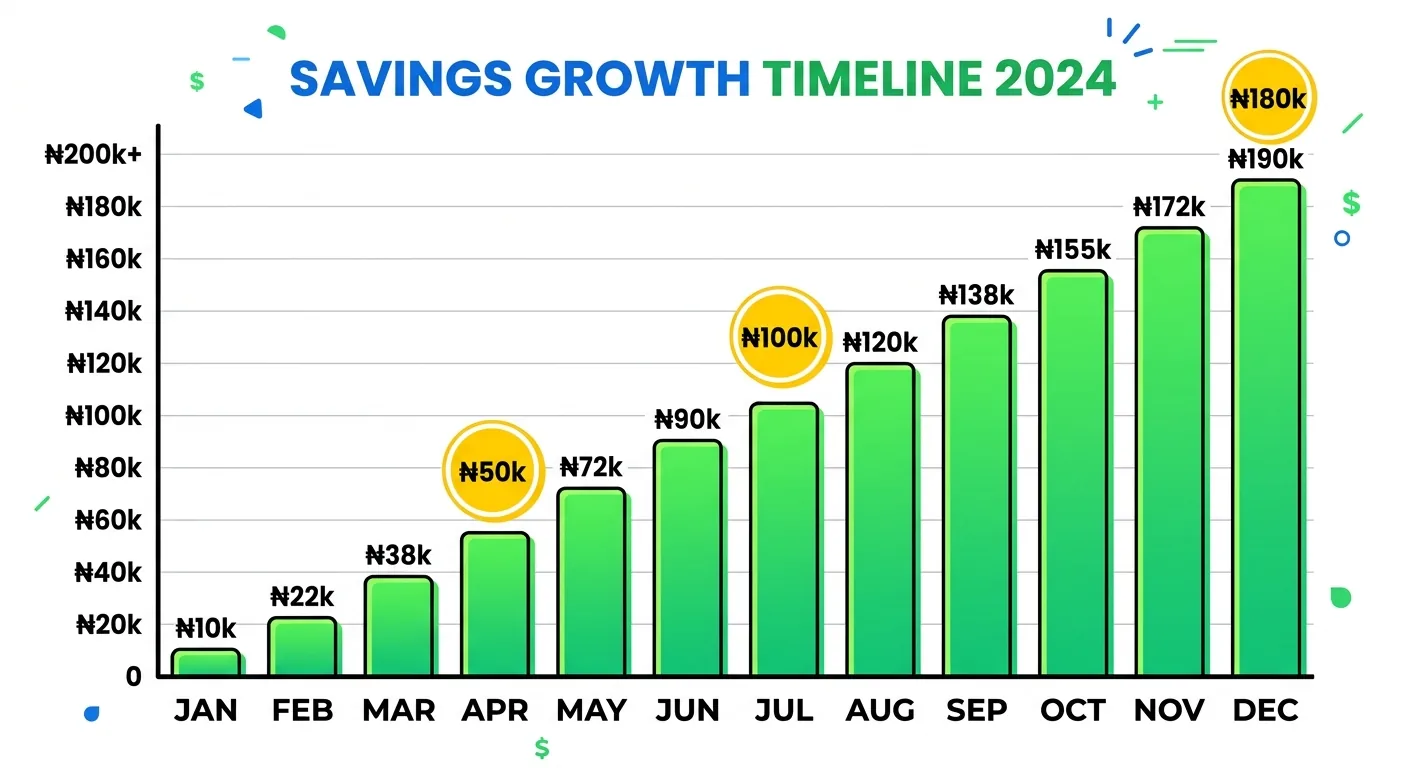
Set ₦500 per day as your automated savings amount on PiggyVest:
- ₦500 × 30 days = ₦15,000 per month
- ₦15,000 × 12 months = ₦180,000 per year
- Add approximately 10% interest = ₦198,000 sitting in your emergency fund
That is close to ₦200,000 available for the January sapa, the unexpected medical bill, the car repair that ambushes you in Lagos traffic with zero warning.
₦500 per day is less than one suya plate and a cold drink. The amount is not the obstacle. The automation removes the daily decision-making that destroys most savings attempts before they reach 30 days.
If ₦500 feels tight, start at ₦200 per day. That still builds ₦72,000 in a year — more than most Nigerian salary earners currently hold in reserve.
How to Lock Your Money So "Urgent" Hands Can't Touch It
The biggest enemy of savings in Nigeria is not poverty. It is accessibility. When money is easy to reach, it gets reached — every time, for every "emergency."
Here is the three-layer strategy using automated savings apps Nigeria workers can deploy immediately:
Layer 1 — PiggyVest SafeLock for your core emergency fund. Lock it for 6–12 months. The penalty for early withdrawal is the feature, not the problem. Your March crisis should not be able to destroy the fund you have been building since January.
Layer 2 — Cowrywise goal-based savings for upcoming known expenses. School fees in September. Rent in December. NYSC relocation costs. These are predictable shocks. Saving for them in advance with a named goal removes the element of surprise.
Layer 3 — Kuda Spend+Save as your daily micro-savings layer. It runs passively in the background — ideal for anyone who finds active financial management mentally exhausting.
The logic is simple: Kuda catches small daily amounts. Cowrywise builds towards known goals. PiggyVest locks away the untouchable emergency core.
The Trap: When Automation Becomes a Problem for Low-Income Earners
This is the section most Nigerian finance articles skip. It will not be skipped here.
If you earn ₦50,000 and you automate ₦15,000 monthly into savings, but your rent is ₦20,000, feeding is ₦18,000, and transport is ₦12,000 — the mathematics does not work. You will either break the savings plan or default on something essential.
Over-automation on a tight income creates a new crisis. It forces you to borrow the money you just saved, wiping out your savings buffer while adding loan interest debt on top. This is not hypothetical — it is the predictable outcome for anyone who sets savings targets without calculating their actual baseline expenses first.
The rule: Never automate more than 10–15% of take-home pay if you earn between ₦50,000 and ₦100,000 monthly. For earners above ₦150,000, 20% is the maximum until you have confirmed surplus over three consecutive months.
Calculate your real expenses first. Then automate the genuine remainder — not the wishful version.
Which Platform Works Best for Your Income Level
| Monthly Income | Recommended Platform | Strategy |
|---|---|---|
| Below ₦50,000 | Kuda Spend+Save | Start at ₦100–₦200/day, build habit before amount |
| ₦50,000 – ₦100,000 | Cowrywise + Kuda | Goal buckets for known costs + daily micro-savings |
| ₦100,000 – ₦200,000 | PiggyVest + Cowrywise | Lock emergency core + separate named goal pockets |
| Above ₦200,000 | All three layered | Full three-layer system for maximum protection |
Choosing the right combination from available automated savings apps Nigeria platforms based on income level is the difference between a savings plan that survives contact with real life and one that collapses by February.
How to Start Today — Even If You Earn ₦50,000 a Month
Step 1: Download PiggyVest, Cowrywise, or Kuda — all three are free on Android and iOS.
Step 2: Link your salary account and set automated deductions to trigger the day your salary arrives — not end of month.
Step 3: Start with an amount that does not hurt. ₦100 per day is not embarrassing. It is a start that beats zero.
Step 4: Set a minimum 3-month lock on your emergency savings portion. Shorter than that and the justification to break it becomes too easy.
Step 5: Forget it exists. Let the automation run. Check back in 90 days.
According to CBN's 2024 Financial Stability Report, digital savings adoption among Nigerian adults under 35 grew by 41% year-on-year — driven almost entirely by mobile-first automated savings apps Nigeria platforms like the three covered in this guide. The infrastructure is in place. The only remaining decision is yours.
Final Verdict: Stop Waiting for "Extra Money" — It Never Comes
There will never be a month where everything is settled and spare cash sits waiting to be saved. Life in Nigeria always produces something new to spend on. That is not pessimism — it is the documented pattern of every salary earner who has said "I will start saving next month" for the last three years.
Automated savings apps Nigeria workers can access today — PiggyVest, Cowrywise, Kuda — do not wait for extra money. They take the money first. Before the suya. Before the unnecessary data bundle. Before the small-small amounts that quietly consume your salary every single month.
These apps are not magic. They are structure. And for Nigerian salary earners navigating the sapa economy in 2025, structure is the closest thing to a financial superpower that ordinary people can access completely free.
Start with ₦200 a day. Lock it. Leave it alone.
By this time next year, your January will feel genuinely different.
Frequently Asked Questions
Are automated savings apps Nigeria platforms like PiggyVest and Cowrywise safe and regulated?
Yes. PiggyVest and Cowrywise both operate under licences and partnerships with CBN-regulated financial institutions. Funds held on PiggyVest are insured through their partner MFB relationships. Cowrywise is SEC-registered for investment products. Kuda Bank holds a full CBN microfinance bank licence. None of these are unregulated fintech startups — they operate within Nigeria's formal financial regulatory framework.
What happens if I need to withdraw early from my PiggyVest SafeLock?
PiggyVest allows early withdrawal from SafeLock but charges a penalty equivalent to 10% of the interest earned on the locked amount — not 10% of your principal. So if you saved ₦100,000 and earned ₦5,000 in interest, the penalty is ₦500, not ₦10,000. Your principal is always returned in full. This penalty structure is deliberately designed to discourage impulse withdrawal while not being punitive enough to cause real financial harm.
Can I use more than one automated savings app at the same time in Nigeria?
Absolutely — and for most salary earners earning above ₦80,000 monthly, using two or three platforms simultaneously in a layered approach is the recommended strategy. Kuda handles daily micro-savings passively, Cowrywise manages named goals like rent and school fees, and PiggyVest locks away the core emergency fund. Each platform serves a different psychological function. Using all three does not create confusion — it creates structure that covers different savings needs simultaneously.
