Your ₦350,000 work laptop is sitting in a cart. Your child's school fees landed this morning like an uninvited guest with no intention of leaving. And your phone — the one held together by a prayer and a cracked screen protector — finally gave up last Tuesday.
For most Nigerian salary earners, the old options were grim: drain your savings, beg family, or swallow a high-interest loan app and spend six months regretting it.
But installment payment plans platforms have quietly rewritten that script. Today you can walk out of a store with a laptop, pay a fraction upfront, and settle the balance in monthly chunks — no credit card, no collateral, no guarantor.
Before you tap that "Split Payment" button, though, read this first. What these platforms show you on their landing pages and what actually happens to your wallet are two very different stories.
What Installment Payment Plans Actually Mean in Plain English
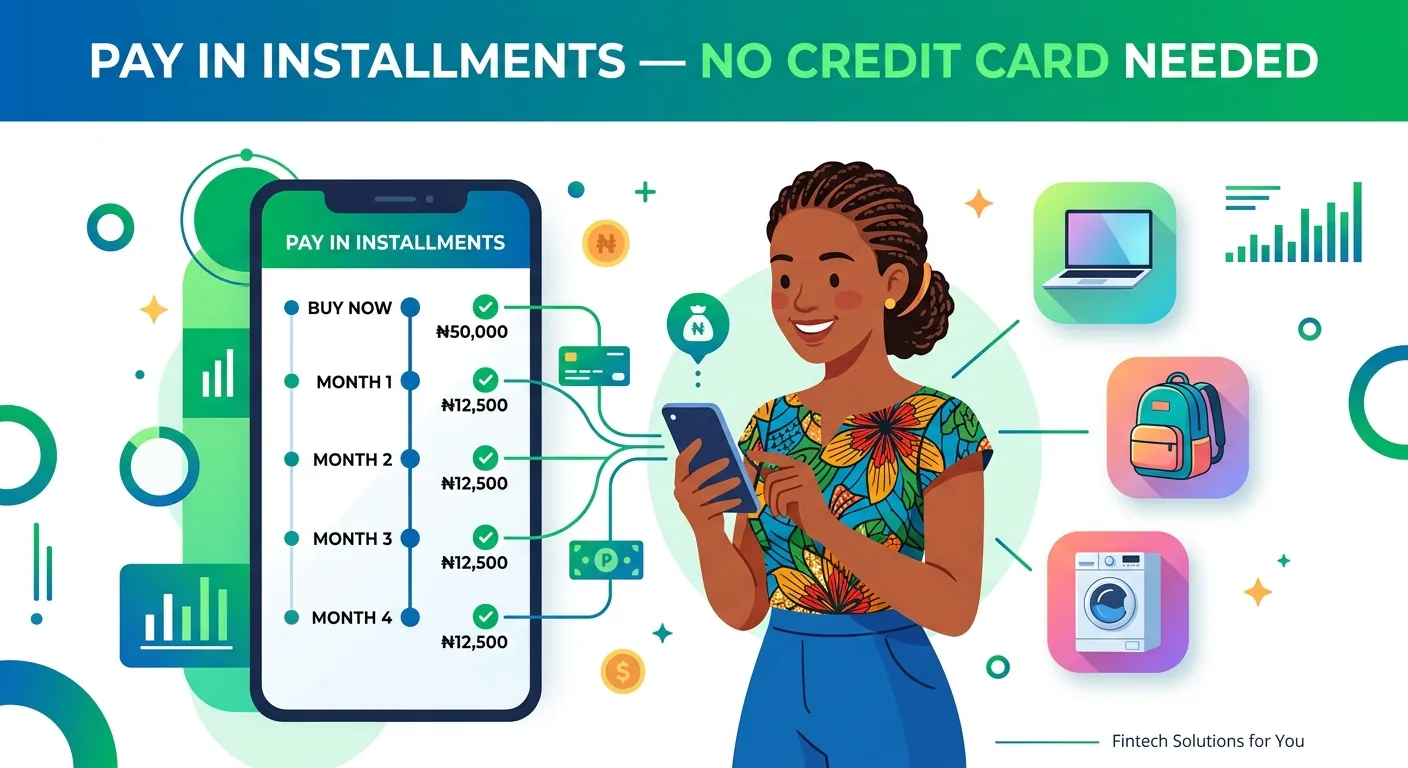
An installment payment plan is straightforward: instead of paying the full price at once, you pay a portion upfront — sometimes zero — collect the item immediately, and repay the remainder in fixed amounts over weeks or months.
In Nigeria, where CBN data shows fewer than 1% of adults hold a credit card, this gap was enormous. BNPL platforms rushed in to fill it.
The basic structure works like this:
- You want a ₦250,000 item
- You pay ₦50,000 upfront
- The remaining ₦200,000 is spread across 3–6 months
- The platform earns a service fee or interest on the outstanding balance
Simple on paper. The complexity lives inside the fee structure — and that is exactly where we are headed next.
How BNPL Installment Apps Work in Nigeria — Step by Step
Most installment payment plans platforms follow a predictable process:
Step 1: Register your account. You provide your BVN, a valid government ID, and your phone number. Some platforms also request your employer's name or three to six months of bank statements.
Step 2: Get pre-approved. The platform queries your BVN-linked credit history through CRC Credit Bureau or FirstCentral and assigns you a spending limit.
Step 3: Shop within their ecosystem. Most platforms operate a built-in store or maintain partnerships with specific retailers. You select your item and choose a repayment schedule.
Step 4: Pay your first installment. Some platforms require a 20–30% deposit. Others offer zero down for verified salary earners.
Step 5: Receive your item immediately. This is the core BNPL value — you take the phone or laptop today, pay the balance later.
Step 6: Repayments are deducted automatically. Either auto-debited from your bank account on a fixed date or deducted at source from your salary if your employer is integrated with the platform.
The Main Platforms Offering Installment Payment Plans in Nigeria
CredPal
One of Nigeria's most established pay in installments platforms. CredPal offers a virtual credit card and a shopping portal covering electronics, appliances, and more. Plans run from 1 to 12 months. Crucially, CredPal reports to credit bureaus — meaning consistent repayment actively builds your credit score.
Best for: Salary earners who want to purchase gadgets and build a formal credit history simultaneously.
CDcare
CDcare runs a zero-interest installment payment model with one key difference — you pay first and receive the item after hitting 50–70% of the total price. It functions more like structured goal savings that ends in ownership.
Best for: Disciplined buyers who want to avoid interest entirely and do not need the item urgently.
Easybuy (Watu Credit)
Easybuy targets smartphones and electronics for lower-income earners. Pay a deposit, walk out with the device the same day. Repayments run weekly or monthly, but the effective interest rate on longer plans can be steep — read the contract carefully.
Best for: Anyone who needs a functional phone urgently and earns below ₦100,000 monthly.
Jumia Pay Later
Jumia has embedded a pay-later option directly inside its shopping cart. Registered users with a positive transaction history can split selected purchases without leaving the platform.
Best for: Regular Jumia shoppers who want frictionless split payment apps Nigeria built into their existing routine.
Salary-Linked BNPL Platforms
Platforms like Carbon (Paylater) and Creditcorp partner directly with employers. Repayments are deducted from your salary before it hits your account, making default structurally near-impossible.
Best for: Civil servants and formal-sector employees with predictable, consistent monthly income.
The Real Cost Comparison — Is Paying in Pieces Cheaper Than a Loan?
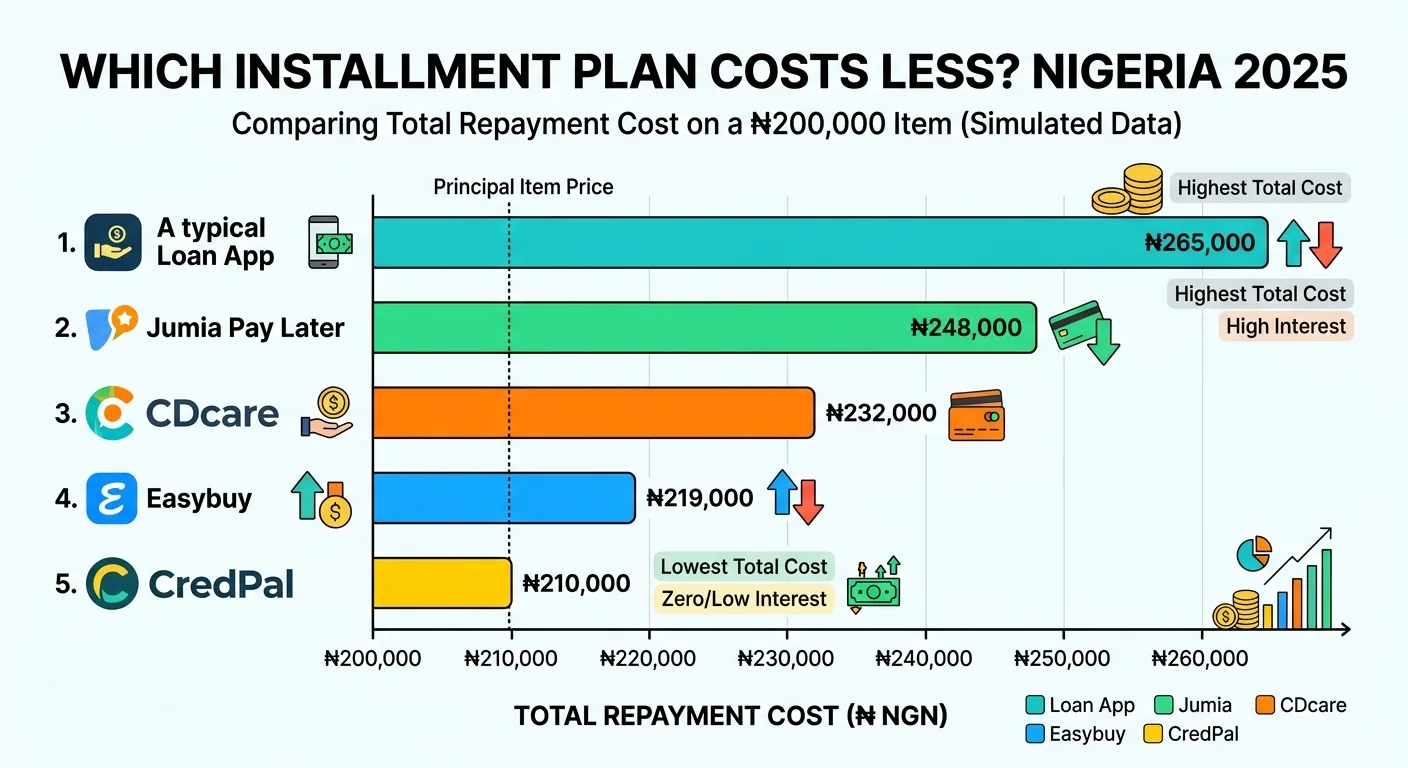
Most people compare only the monthly payment, not the total payout. Here is a clear breakdown on a ₦200,000 laptop across your main options:
| Option | Down Payment | Monthly Payment | Total Paid |
|---|---|---|---|
| Cash (one-time) | ₦200,000 | None | ₦200,000 |
| CredPal (6 months, ~5% monthly) | ₦40,000 | ~₦30,000 | ₦220,000 |
| FairMoney Loan (6 months) | ₦0 | ~₦38,000 | ₦228,000 |
| CDcare (zero interest) | Monthly savings | Delivery at threshold | ₦200,000 |
| Easybuy | ₦30,000 | Varies | ₦240,000–₦270,000 |
CDcare costs the least overall but demands patience — the item stays with the platform until you cross the payment threshold.
CredPal offers the sharpest balance between upfront convenience and total cost.
Easybuy is fastest to access but most expensive over the full repayment term.
The cheapest installment payment plan in Nigeria is not always the most visible one in a Google search.
Who Qualifies for Installment Payment Plans in Nigeria?
Ignore the "no collateral, no wahala" marketing for a moment. Every platform on this list assesses you — they have simply modernized how they do it:
- BVN — mandatory for identity verification and bureau access
- Credit bureau history — CRC or FirstCentral records of previous defaults matter significantly
- Employment status — formal salary earners receive higher limits than self-employed applicants
- Bank statement analysis — three to six months of consistent, verifiable income
- Phone number age — newly registered SIM cards are often flagged as higher risk
- Contact and SMS access — some smaller platforms still request this despite FCCPC guidelines prohibiting the practice
NYSC corpers and students are not automatically excluded. Corpers with an active BVN and a verifiable NYSC allowance history can access entry-level BNPL for salary earners Nigeria plans, typically with lower initial limits that grow with repayment history.
The Hidden Risks Nobody Mentions Before You Click Split Payment
1. The effective rate is far higher than the headline number.
A "5% monthly fee" on ₦200,000 equals ₦10,000 every month — ₦60,000 extra across six months. Annualized, that is a 60% cost of credit. Know your numbers before you sign anything.
2. One missed payment can spiral fast.
Late fees compound quickly. Several platforms lock your account after a single missed deduction and report the default to credit bureaus immediately, damaging your eligibility for future installment payment plans Nigeria products.
3. Product disputes do not pause your repayments.
If the device you bought is faulty, you still owe every installment. The financing entity is legally separate from the retailer. You will be chasing the seller while simultaneously paying the platform.
4. Impulse buying disguised as affordability.
This is the biggest risk of all. A ₦400,000 television split into ₦35,000 per month feels painless — until you are running three concurrent plans and your net salary barely covers the combined deductions. The platforms understand your psychology. The question is whether you do.
Smart Rules Before You Sign Any Installment Plan
Rule 1: Always calculate the total cost, not just the monthly amount.
Multiply monthly payment by the number of months. Compare that figure to the cash price. The difference is the real price of convenience.
Rule 2: Never carry more than two installment plans simultaneously.
Concurrent plans are the most common path into debt trouble — not a single reckless decision, but a slow accumulation of small commitments.
Rule 3: Reserve installment plans for productive purchases only.
Work laptops, business phones, school fees, medical equipment — these justify installment payment plans. A new television when the current one works? That is deferred sapa, not smart finance.
Rule 4: Check whether the platform reports to credit bureaus.
If it does, disciplined repayment builds your credit score — a genuine long-term asset. If it does not, you are paying interest with zero benefit to your financial future.
Rule 5: Verify FCCPC registration before you submit your BVN.
Unregistered buy now pay later electronics Nigeria platforms operate in a regulatory grey zone. Your data and money carry substantially more risk outside of licensed operators.
Verdict — When Installment Plans Work and When They Don't
Installment payment plans make sense when:
- You need a productive item urgently and your income is stable and predictable
- The total repayment cost is lower than a comparable loan app product
- You have only one active plan running at the time
- The platform is FCCPC-registered and discloses all fees before you commit
Installment payment plans do NOT make sense when:
- You already have active loan repayments reducing your take-home pay
- You cannot state the exact total repayment amount before signing
- The platform requests contact list or SMS access at registration
- Your income is irregular — commission-based, new employment, or contract roles
Final Word
Installment payment plans in Nigeria are among the most genuinely useful financial products to enter the mass market this decade. For the salary earner who needed a work laptop and could not produce ₦250,000 at once, BNPL is a real and legitimate lifeline.
But financial tools carry no loyalty. They serve whoever understands them best — and these platforms have invested heavily in understanding you.
Calculate your total cost. Limit your concurrent plans. Buy only what improves your income or your life in a direct, measurable way.
Do that consistently, and installment payment plans become a tool that works for you. Do the opposite, and you will spend months paying for a cracked screen on a plan you cannot exit.
Sharp-sharp is not only about moving fast. It is about thinking faster than the platform selling you convenience.
